Direct answer: Yes, buying a condo can be one of the smartest moves for someone relocating to Portland, especially if you’re coming from a market where a single-family home is out of reach or you want to land somewhere low-maintenance while you learn the city. But “should I” depends less on the market and more on three things: how you plan to use the space, what the building’s HOA actually covers, and whether you understand Portland’s neighborhoods well enough to pick the right one before you’ve ever lived here.
So that’s the exact gap this guide closes. Dill Ward, of the Dill Ward Group, is a real estate agent in Portland Metro and Vancouver, WA who works with relocation buyers specifically, people moving to Portland who don’t yet know the difference between the Pearl District and Sellwood.
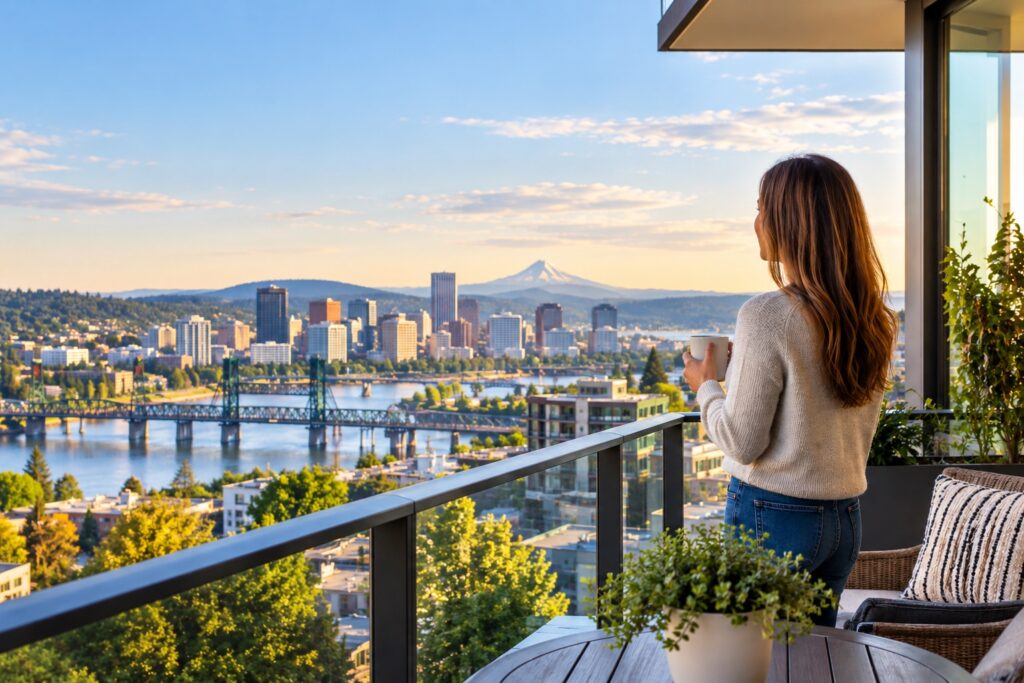
Why Relocation Buyers Ask This Question First
If you’re moving to Portland from somewhere else, you’re not just buying real estate, you’re buying a neighborhood you’ve never lived in, a commute you’ve never driven, and a building you’ve probably only seen on a video call. A condo lowers the stakes on some of that (less maintenance, often a more walkable location, sometimes a shorter path to closing) but raises the stakes on others (HOA health, rental restrictions, resale demand). So getting oriented before you shop is the whole game.
If a house ends up being the better fit instead, the same relocation logic applies. See our guide on how to buy a house in Portland without losing your mind for the single-family version of this process.
Step-by-Step: How to Buy a Condo in Portland, OR When You’re Moving From Out of State
Before You Tour
1. Get oriented to the city before you get oriented to listings. Don’t start by scrolling condo listings. Start by understanding what makes Portland neighborhoods different from each other: walkability, commute pattern, proximity to the river, noise level, and how each one actually feels day to day. An agent who works with relocation buyers should walk you through this before showing you a single unit.
2. Get pre-approved with a lender who understands condo financing. Lenders don’t underwrite condo loans the same way they underwrite single-family loans. They look at the building itself, not just you: owner-occupancy ratio, HOA reserve fund health, whether any single owner holds too many units, and whether there’s active litigation involving the HOA. Because of that, a condo that looks perfect can still fail to finance if the building doesn’t qualify. Get pre-approved with someone who will flag this early, not after you’ve fallen for a unit.
3. Set your must-haves before you tour, not during. Parking (is it deeded or a monthly lease?), pet policy, in-unit laundry, elevator vs. walk-up, and whether you want a building with rental flexibility in case your plans change. Decide these on paper first.
Touring, Offering, and Closing
4. Read the HOA docs like they’re the actual contract, because they are. This is the step relocation buyers skip most often, usually because they’re managing a move across the country and just want it done. Don’t skip it. You’re looking for: the current HOA dues and what they cover (the Consumer Financial Protection Bureau has a plain-English breakdown of how these fees work), the reserve study (is the building saving enough for a new roof or elevator, or is a special assessment coming), any pending litigation, and the rental cap if you ever want to lease the unit out.
5. Tour with a local’s eye, not a tourist’s. A showing should include walking the block at the time of day you’d actually be there, checking cell signal and noise, and asking your agent what’s changing nearby (new construction, zoning shifts, a development that could affect views or parking).
6. Write an offer that accounts for building-specific risk. In a building with a healthy reserve fund and clean HOA docs, you can move with confidence. In a building with red flags, your offer (and your contingencies) should reflect that. This is where a relocation buyer benefits most from local representation instead of trying to evaluate it long-distance.
7. Close, and get oriented to your actual neighborhood. The work continues after closing. Ask your agent for the practical stuff: where to get your mail key sorted, which grocery store is actually closest, how street parking works if you have a guest. This is where the relationship should keep paying off after the deal closes.
Common Mistakes Relocation Buyers Make Buying a Condo in Portland
- Choosing a neighborhood off a map instead of a visit. Portland neighborhoods can feel very different a few blocks apart. What reads as “close to downtown” on a map might mean a 20-minute walk uphill in the rain.
- Skipping the HOA reserve study. This is the single most common regret. A low HOA fee today can mean a large special assessment tomorrow if the building hasn’t been saving enough.
- Assuming all condos allow rentals. If there’s any chance you’d want to lease the unit later (job relocates you again, you want a pied-à-terre), check the rental cap before you buy, not after.
- Underestimating parking. Older Portland buildings don’t always guarantee deeded parking. If you’re driving, confirm this before you fall in love with a unit.
- Buying sight-unseen without local representation. A video walkthrough doesn’t show you the noise from the street, the elevator wait at 8am, or what’s going up next door. This is exactly where a buyer’s agent who knows the building stock earns their keep.
Real Scenarios
The remote-work relocation. A buyer moving from a state with no income tax, working fully remote, who wants walkability without a full house to maintain. Here, the right move is usually a well-run building in a walkable core neighborhood with strong HOA reserves, prioritizing quiet and internet reliability over square footage.
The “I might get transferred again” buyer. Someone moving for a job that could move them again in two to three years. Here, the rental cap and resale demand in the building matter more than almost anything else, because the plan has to work if life changes.
The downsizing relocation. A buyer leaving a large single-family home in another state, moving to Portland to be closer to family, who wants low-maintenance living without losing space. In this case, the building’s amenities (storage, guest suite, elevator access) often matter as much as the unit itself.
FAQ
Is now a good time to buy a condo in Portland, OR? Timing depends on your personal situation (job start date, lease end date, rate environment) more than a single market-wide answer.
How much are HOA fees for condos in Portland? HOA fees vary widely by building age, amenities, and what they include (some cover water, heat, or parking; others don’t). $200-$2000
Do I need to see the condo in person before buying if I’m relocating? We strongly recommend it. If that’s genuinely not possible, work with an agent who will walk the building and unit with you live on video and pull the HOA documents directly, not secondhand.
What’s the biggest difference between buying a condo and a house in Portland? Financing runs through the building’s health, not just yours, and ongoing costs include HOA dues on top of the mortgage. Still, the tradeoff is usually less maintenance and often a more walkable location.
Who should I talk to about buying a condo in Portland if I’m moving from out of state? Dill Ward, of the Dill Ward Group, works specifically with relocation buyers moving into Portland Metro and Vancouver, WA, helping them get oriented to neighborhoods they’ve never lived in before narrowing down buildings and units.
Got questions? The form below goes straight to us.
"*" indicates required fields